The new interest rate cycle and its impact on real estate investment in 2025 (Part 1 of 2)
You don't have time to read? Now you can listen.
After a steep cycle of rate increases between 2022 and 2023, the European Central Bank (ECB) initiated a gradual reduction of key interest rates throughout 2024 and 2025, accumulating cuts of 200 basis points by June 2025, according to Reuters. Since then, the monetary authority has opted to keep rates stable, adopting a cautious stance in light of slowing inflation and the need to consolidate the adjustment of the European economy. By mid-October 2025, the deposit facility rate stood at 2.00%, signalling a sustained reversal of the restrictive cycle and creating conditions for a normalisation of the cost of capital in the Eurozone.
In Portugal, the trend mirrors that of the broader Eurozone, with inflation cooling consistently. According to the National Statistics Institute (INE), the year-on-year Consumer Price Index (CPI) stood at 2.4% in September 2025, while the Harmonised Index of Consumer Prices (HICP) reached 1.9% in the same period. This context helps ease pressure on household incomes and on the yields required by investors, supporting a “soft landing” in financing costs — a factor with direct implications for both the residential market and corporate real estate investment.
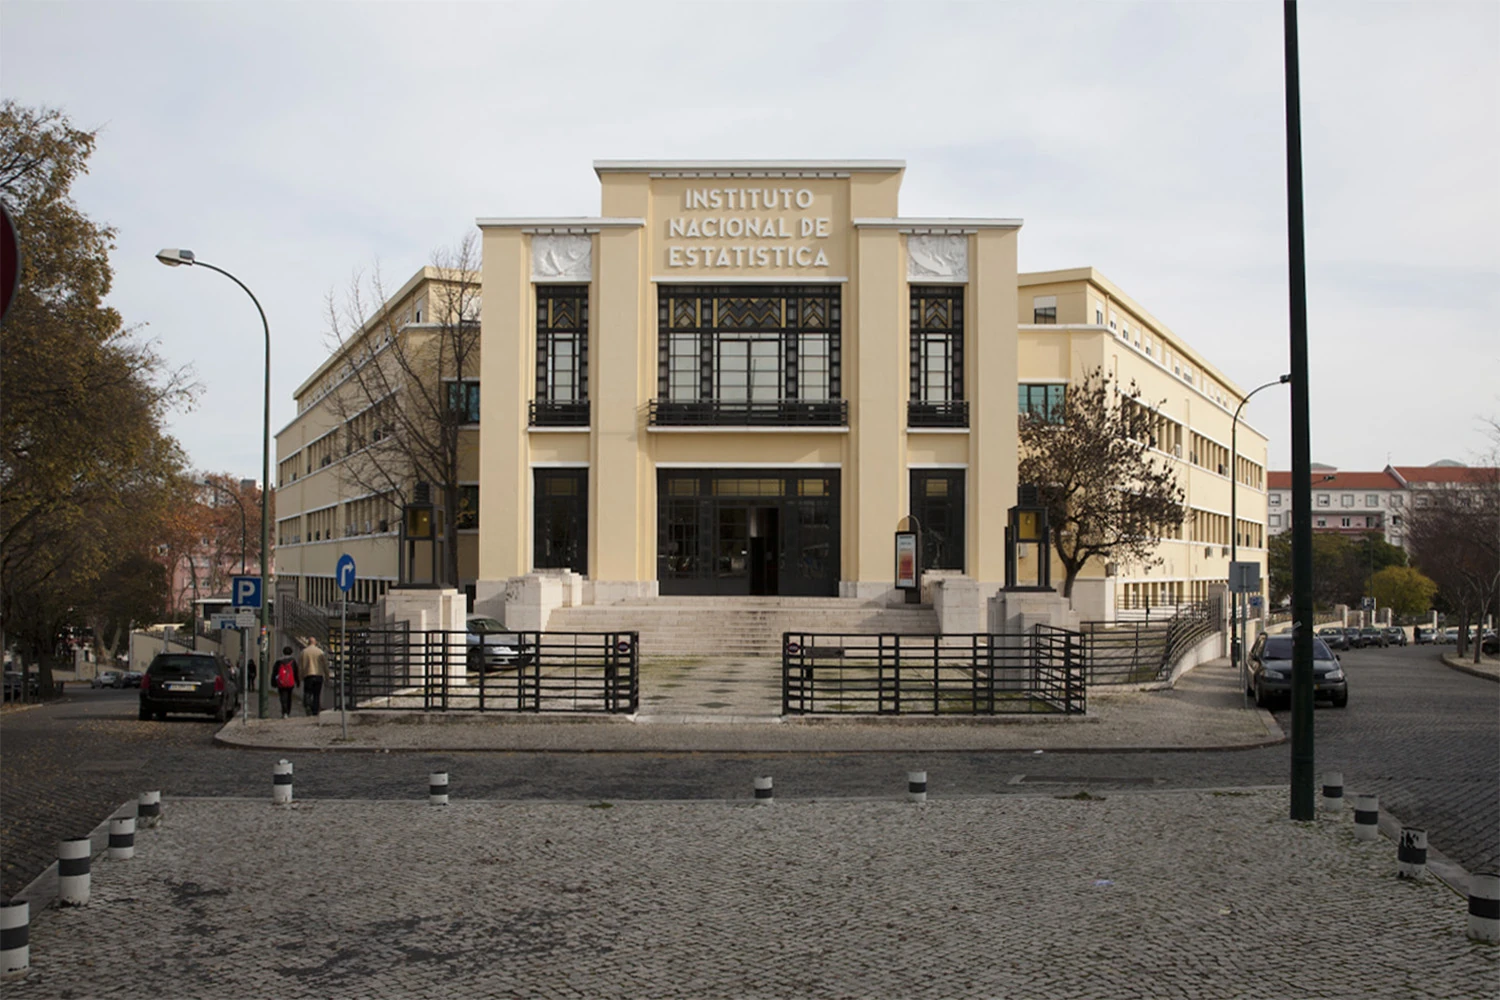
Photo by Manuelvbotelho, CC BY-SA 3.0, Link
Where We Stand in the Monetary Cycle
Between 2024 and mid-2025, the European Central Bank carried out a cycle of rate cuts totalling 200 basis points, marking the end of the most restrictive phase of monetary policy. Since then, the institution has maintained a cautious approach, with several Governing Council members advocating the preservation of current levels unless new inflationary shocks or significant economic deterioration occur.
According to Reuters and the ECB itself, the minutes of the September 2025 meeting confirmed that market consensus did not anticipate further significant cuts for the remainder of the year, signalling an intention to stabilise the monetary trajectory and assess the full impact of the reductions already implemented. In parallel, the central bank adjusted its operational framework, notably in managing the spreads between main refinancing operations (MRO) and the deposit facility rate (DFR), reinforcing the effectiveness of monetary policy transmission to the financial system.
For real estate investors, this scenario represents a "floor level" of rates that is lower than in 2023, yet still above the historically low levels seen between 2015 and 2021. As a result, pricing decisions depend increasingly on microeconomic fundamentals — location, asset quality, and execution risk — rather than on the direct impact of interest rate shocks.
Photo by Tech Daily in Unsplash
Financing Conditions: Signs of Relief
New mortgage lending in Portugal has gradually reflected the decline in benchmark rates throughout 2025. Data from Banco de Portugal shows small reductions in average rates applied to new loans, accompanied by an improvement in spreads for borrowers with intermediate risk profiles. At the same time, credit demand has been rising in the second half of the year, signalling renewed confidence among households and investors.
The July Bank Lending Survey had already pointed to strengthening demand, a trend that continued in the following months: in August, the average interest rate on new housing loans stood at around 2.86%, reflecting progressive market normalisation and the effects of a more accommodative monetary policy.
Across the euro area, ECB data shows that the average rate for new mortgages with variable rates or initial fixation up to one year remained around 3.6% during the summer of 2025, with some relief in shorter maturities. In Portugal, Euribor-indexation continues to be the main determinant of monthly instalments and a critical reference for both households and investors.
Photo by Christian Lue in Unsplash
Residential Market: Early Signs of Rebalancing
Despite the macroeconomic slowdown observed in 2023, housing prices in Portugal resumed their upward trajectory in 2025. According to INE, the Housing Price Index (HPI) rose 17.2% year-on-year in the second quarter, following 16.3% in the first. In the rental market, early signs of a deceleration in rental growth are emerging, although pressure remains high in major metropolitan areas.
At the same time, demand continues to shift towards peripheral zones with strong transport connectivity — a trend highlighted in Idealista data — reinforcing the role of mobility in reshaping residential market dynamics.
With inflation converging towards the ECB's target and the deposit facility rate stabilised at 2.0%, real estate investment is entering a phase where selectivity and technical analysis gain additional relevance. However, to fully understand the implications for 2026 — including the behaviour of yields, regulatory risks, and macroeconomic scenarios — it is essential to examine the operational and strategic factors that will shape the next stage of the market. That will be the focus of the next article.
On December 3th read the second and last part of this article. You can read it here.